

When are you considered overindebted?
You often only realize how quickly you can end up in the red when your account is already in the red and the outstanding bills are piling up on the kitchen table. If you wait too long to pay off your debts, it's almost impossible to get out of the debt spiral without outside help.
Read more in this article:
When am I in debt? What is over-indebtedness?
If you have taken out a loan and repay the installments on time, this is not a precarious situation. You may be in debt, but your livelihood is not at risk.
However, if you are unable to pay the agreed installments, this is referred to as over-indebtedness - i.e. whenever, after deducting rent, electricity and the costs of daily living, the remaining money is permanently insufficient to meet further payment obligations.
If this happens, you should react quickly and visit a debt advice center. If you don't do this and more and more debts accumulate, there is the threat of reminder proceedings and compulsory enforcement.
My First Apartment: Tips for Saving Money
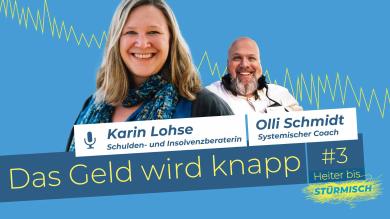
Podcast: Saving Money | Tips for When Money Is Tight
Over-indebted through no fault of your own: Unemployment, divorce, illness
Over-indebtedness can occur completely "through no fault of your own". The "classic" reason is sudden unemployment. But divorce and separation are also among the most frequently cited reasons why people are suddenly no longer able to support themselves.
Especially after a divorce, alimony payments can take a heavy toll, and monthly payments to former partners and for shared children can quickly add up to costs that are difficult to control. However, long-term and serious illnesses are also cited as causes of excessive debt.
Young people often have money problems
Careless and too relaxed handling of money often leads to ending up in the red. Young people in particular have money problems.
In 2024, a total of 5.67 million people in Germany were overindebted. This represents an increase of 111,000 cases compared to 2023. Since 2016 (the last significant increase), the number of overindebted people had been on a downward trend, which is why these new developments are cause for concern.
People in the 30–39 age group are the most indebted.
But people between the ages of 20 and 25 also sought debt counseling in 2016. On average, they had about 7,500 euros in debt, according to the Federal Statistical Office (Statistics on Over-Indebtedness Among Private Individuals, 2017). For many young people, their outstanding cell phone bills alone amount to several times their monthly income.
The cause of excessive debt among young people is particularly alarming. While adults typically accumulate more and more debt due to unemployment, separation, or illness, the cause among young people is “poor financial management.” In other words: They simply consume too much. Gym memberships, subscriptions, online clothing purchases, spending money on video games, and “buy now, pay later” offers—which are nothing more than mini-loans—are particularly appealing and therefore especially dangerous: Very few young people are prepared to handle money.
Budget Guide for Young Households
How can I avoid debt?
Once a person or household has fallen into over-indebtedness, it is difficult to get out of the debt spiral again. At some point, more and more bills and reminders start arriving. Creditors, debt collection agencies and bailiffs try to collect money.
It is best to take the initiative as soon as you notice that you are slipping further and further into the red and can no longer pay outstanding bills:
- A budget book helps you to get a better overview of your monthly income and expenditure.
- Think about where you can cut back on expenses (e.g., eating out less often or skipping your daily coffee to go, taking a two-week vacation instead of a three-week one), and check whether you still need certain contracts, insurance policies, and subscriptions, etc.
- Seek out a debt counseling center that will help you identify the causes and reasons for your debt, work with you to create a budget plan and develop a strategy to gradually reduce your debt.
Counseling for Financial Problems, Debts, or Debt Burdens
It is best to speak to a well-trained income and budget advisor to find out whether this is really feasible and the right path for you.
The pme Familienservice Group offers free budget counseling to employees of its client companies.
Find out more now: pme Assistance
FAQ – Frequently Asked Questions About Excessive Debt
When are you considered overindebted?
You are considered to be in debt when, after paying rent, electricity, and daily living expenses, you consistently do not have enough money left to cover your ongoing obligations. Payment reminders or regularly unpaid bills are early warning signs that you should address immediately.
What is the difference between debt and excessive debt?
Being in debt means that you have loans or obligations that are being repaid on schedule. Over-indebtedness occurs when you are no longer able to make payments on a long-term basis.
What are the typical causes of excessive debt?
Common causes of excessive debt include sudden unemployment, separation or divorce, and prolonged illness; among young people, uncontrolled spending (subscriptions, “buy now, pay later” services, and in-app purchases) is a frequent cause.
How can I prevent excessive debt?
Keep a household budget for two to three months to track your income and expenses and identify any potential cash flow shortfall. It’s helpful to build up an emergency fund (equivalent to two to three months’ salary), review your contracts and subscriptions regularly, cancel any unnecessary ones, and set up automatic savings contributions.
What immediate steps can you take when payment problems arise?
As soon as payment difficulties become apparent, you should prioritize essential payments such as rent and utilities, contact creditors early on to request installment or deferral agreements, and review recurring payments to cancel any unnecessary recurring expenses. Keep track of collection letters and note deadlines so you can respond in a timely manner before legal action is taken.
When and how should I seek professional debt counseling?
Seek professional debt counseling as soon as you notice a persistent shortfall in your household budget, receive payment reminders or collection notices, or face the threat of foreclosure. Prepare all relevant documents for your counseling appointment—bank statements, proof of income, rental agreement, payment reminders, loan agreements, and a list of current subscriptions—as this will speed up the analysis and enable concrete negotiation strategies with creditors.